Pensions & tax
KRA Tax Amnesty 2026: How to Waive 100% of Penalties and Interest
The Kenya Revenue Authority will wipe penalties, interest and fines on tax debts up to 31 December 2025, if you pay the principal by 31 December 2026. Here is who qualifies, what to do on iTax and what happens if you wait.
About 7 weeks left to pay your principal tax and keep the waiver.
The window closes on 31 December 2026. Pay your principal tax before then to keep the 100% waiver.
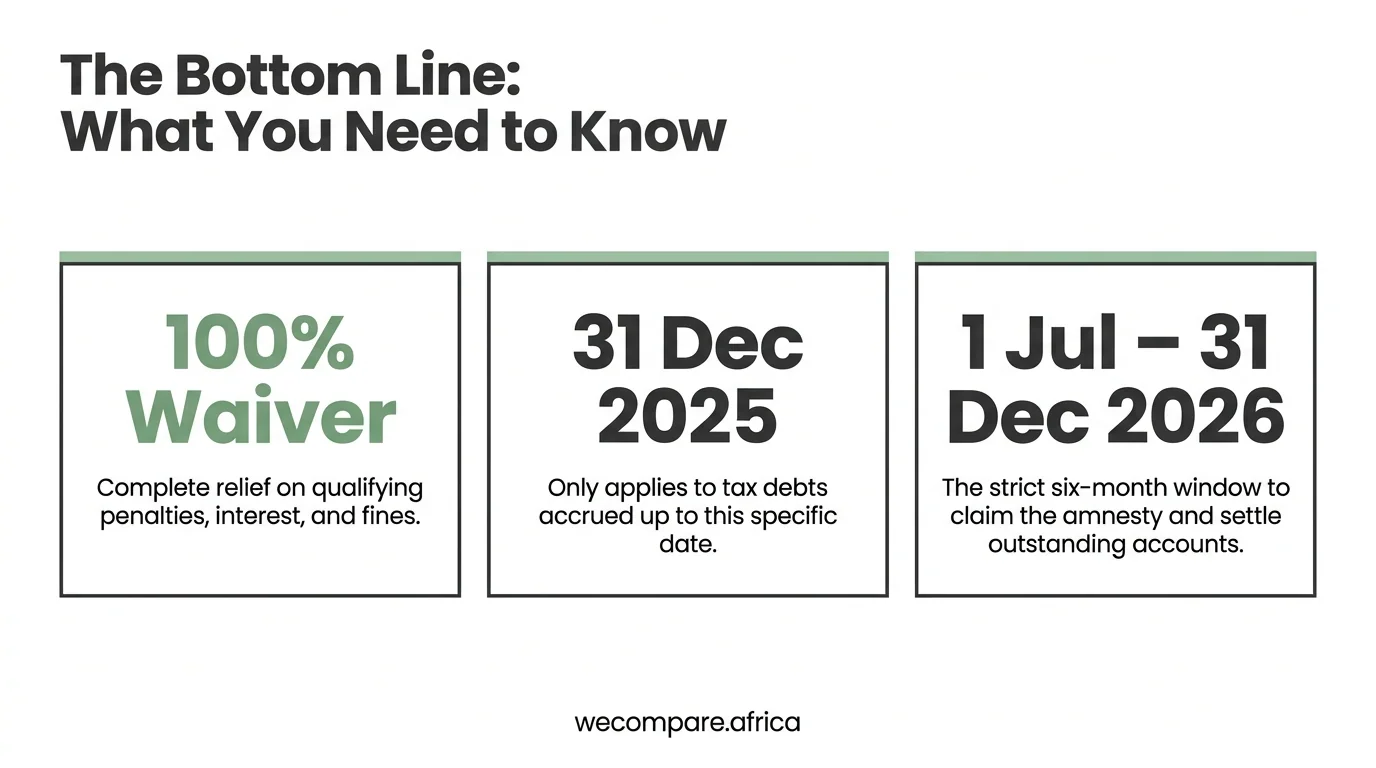
The bottom line
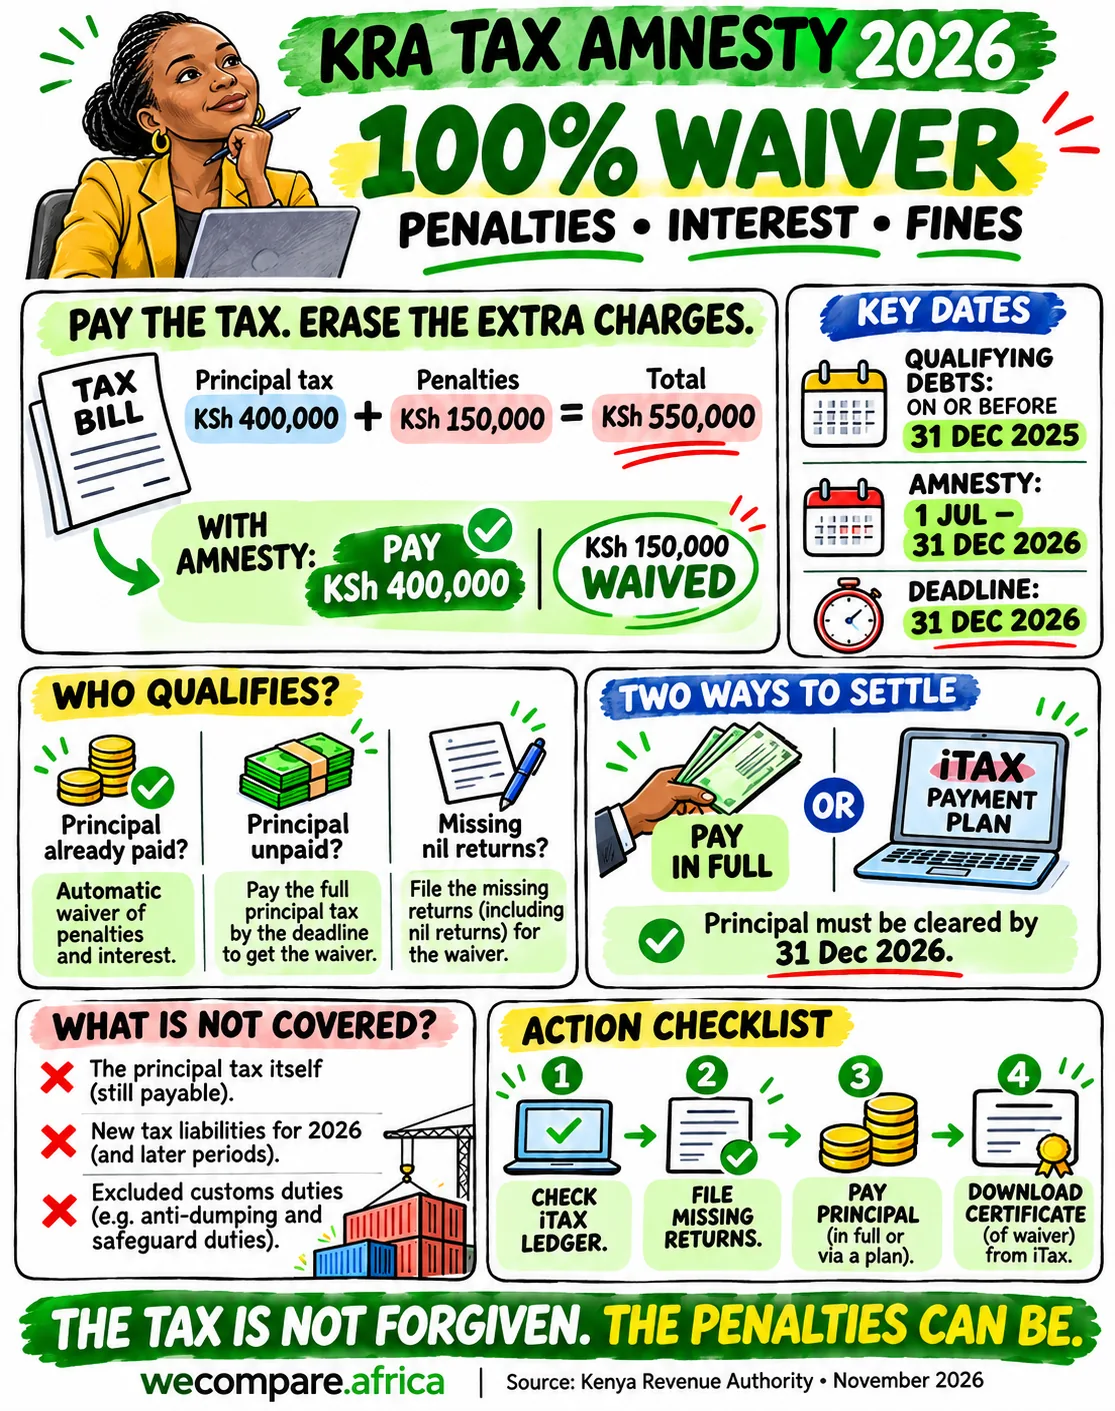
The 2026 amnesty was introduced under the Finance Act 2026 and runs from 1 July to 31 December 2026. It gives a 100% waiver of penalties, interest and fines on tax liabilities that accrued on or before 31 December 2025. The tax itself is not cancelled.
| Item | Detail |
|---|---|
| Window | 1 July 2026 to 31 December 2026 |
| Debts that qualify | Accrued on or before 31 December 2025 |
| What is waived | 100% of penalties, interest and fines under the Tax Procedures Act |
| What you must pay | All principal tax, in full, by 31 December 2026 |
| After 31 December 2026 | Unpaid principal attracts interest and penalties again, with no amnesty |
The core rule: pay the principal, lose the penalties
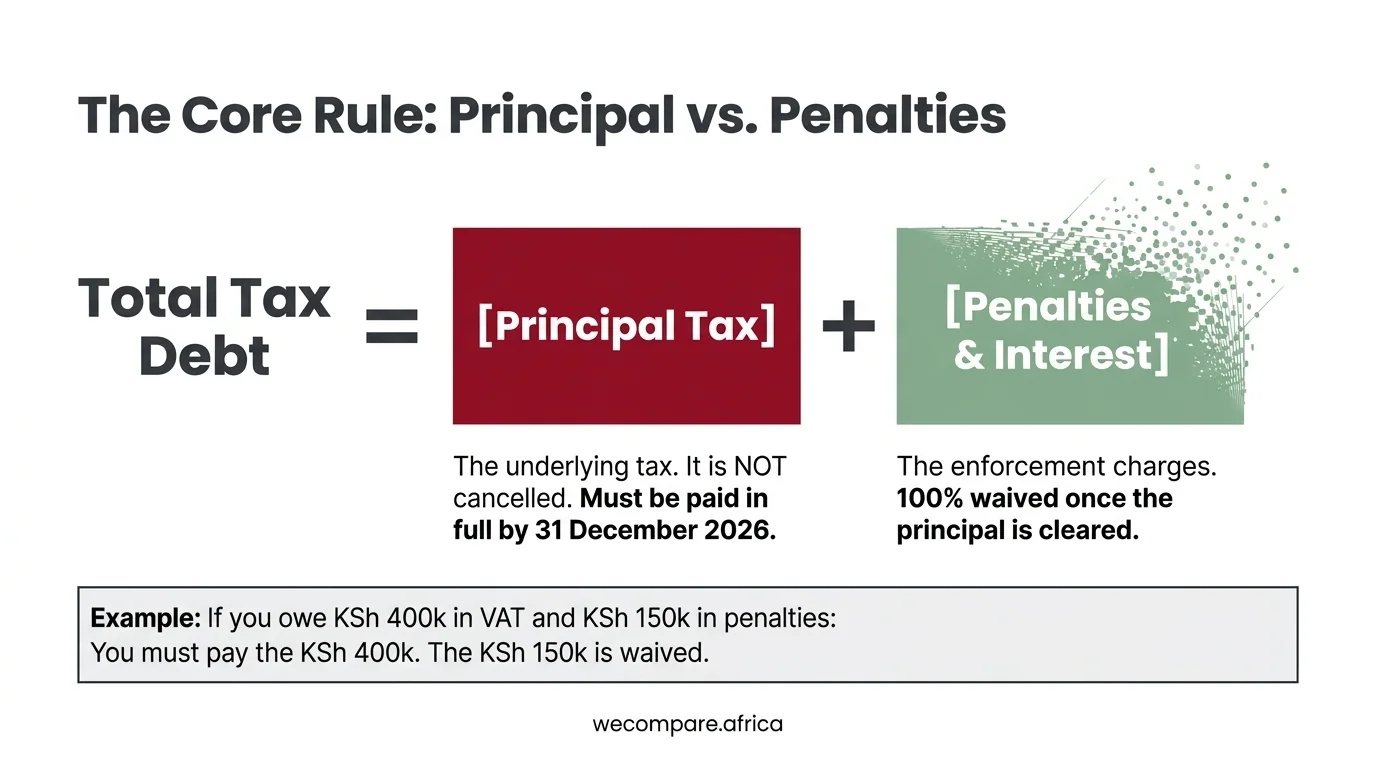
Think of your tax debt as two parts. The principal is the tax you owe. Penalties and interest are the enforcement charges KRA added on top. The amnesty removes the second part once you clear the first.
The critical timeline
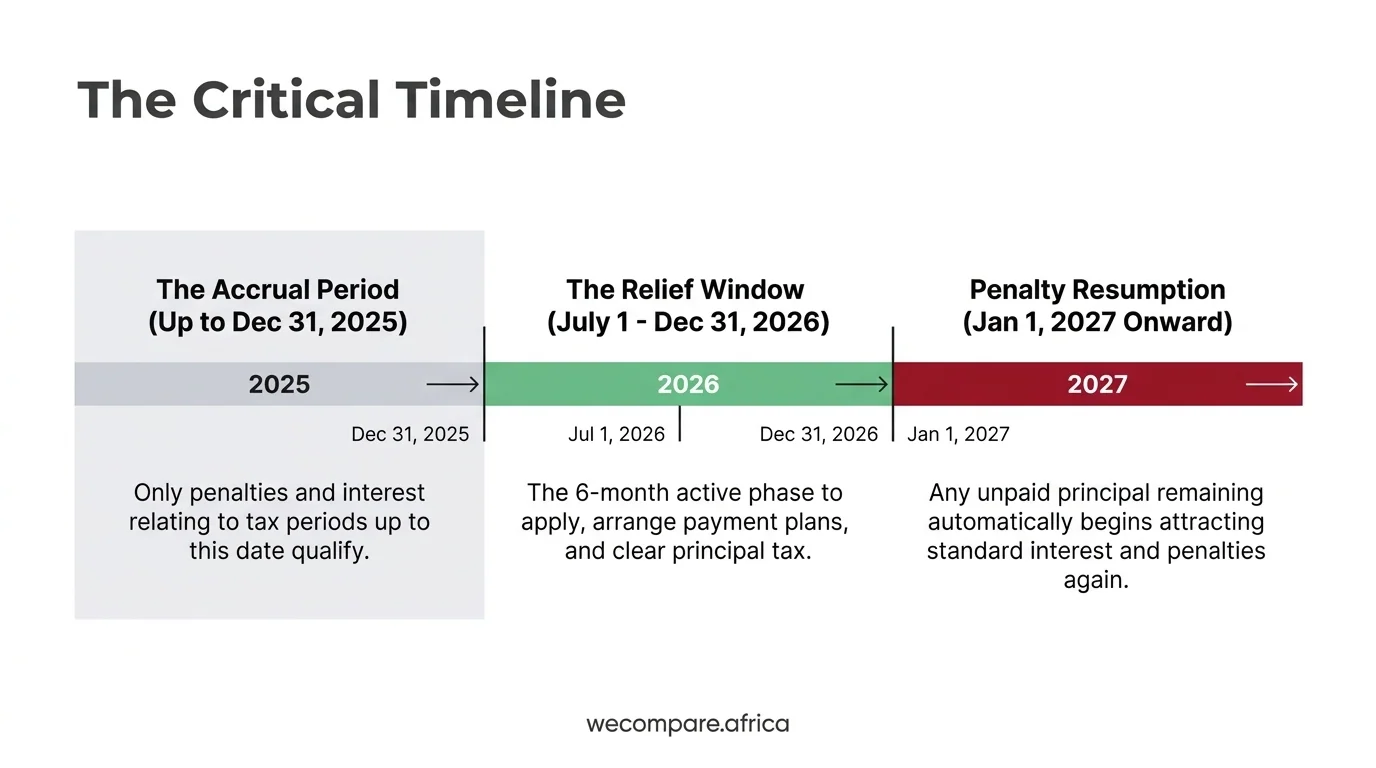
Only debts up to 31 December 2025 qualify. You then have from 1 July to 31 December 2026 to apply, arrange a payment plan and clear the principal. From 1 January 2027, anything still unpaid starts attracting standard interest and penalties again.
Are you eligible? Find your situation
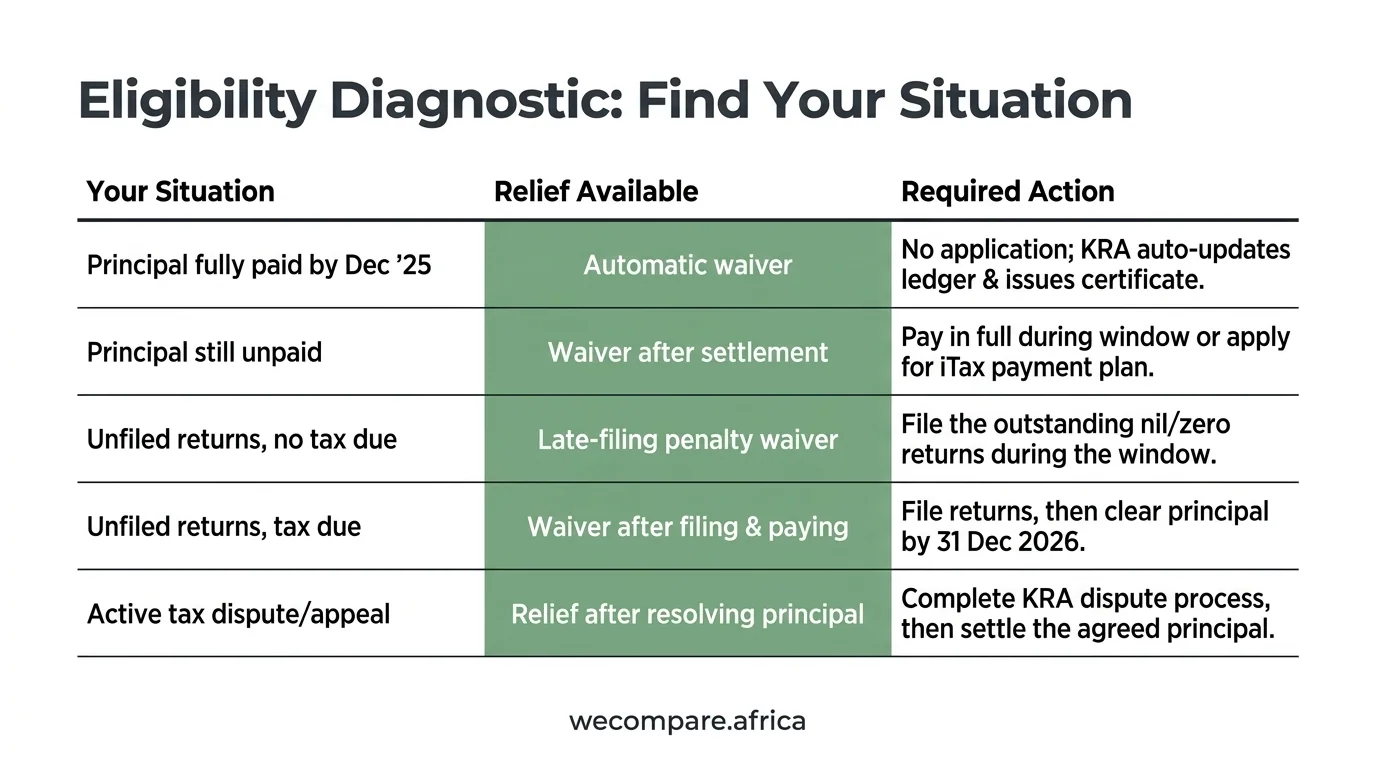
KRA groups taxpayers by what they still owe. Find the row that matches you and follow the action in the last column.
What is covered and what is not
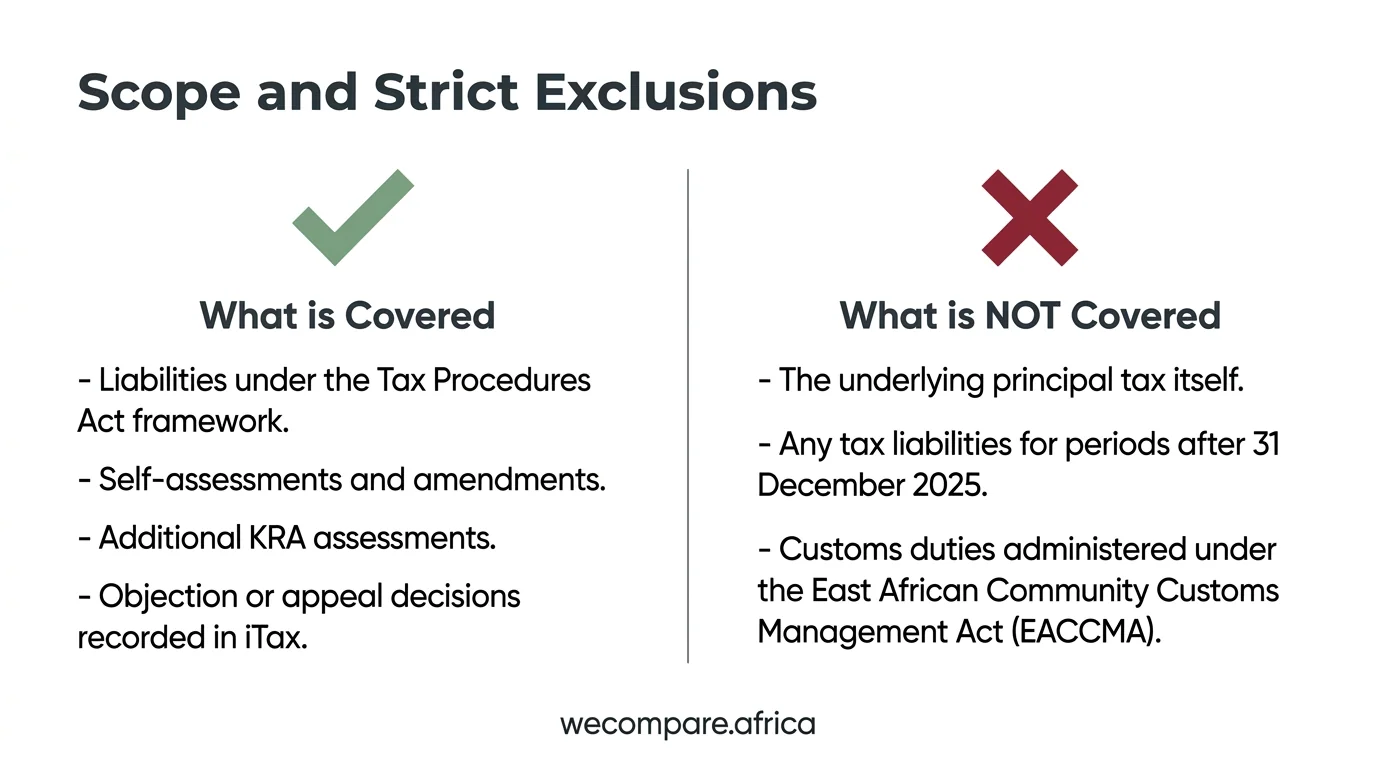
The amnesty applies to amounts imposed under the Tax Procedures Act, including self-assessments, amendments, additional KRA assessments and objection or appeal decisions recorded in iTax. It does not touch the principal tax, charges for periods from 1 January 2026, customs duties under the East African Community Customs Management Act, or agency revenues.
Pathway 1: the automatic waiver
If you already paid all principal for periods up to 31 December 2025, you do not need to apply. iTax finds accounts with a zero principal balance, removes the related penalties, interest and fines from your ledger and generates an amnesty certificate.
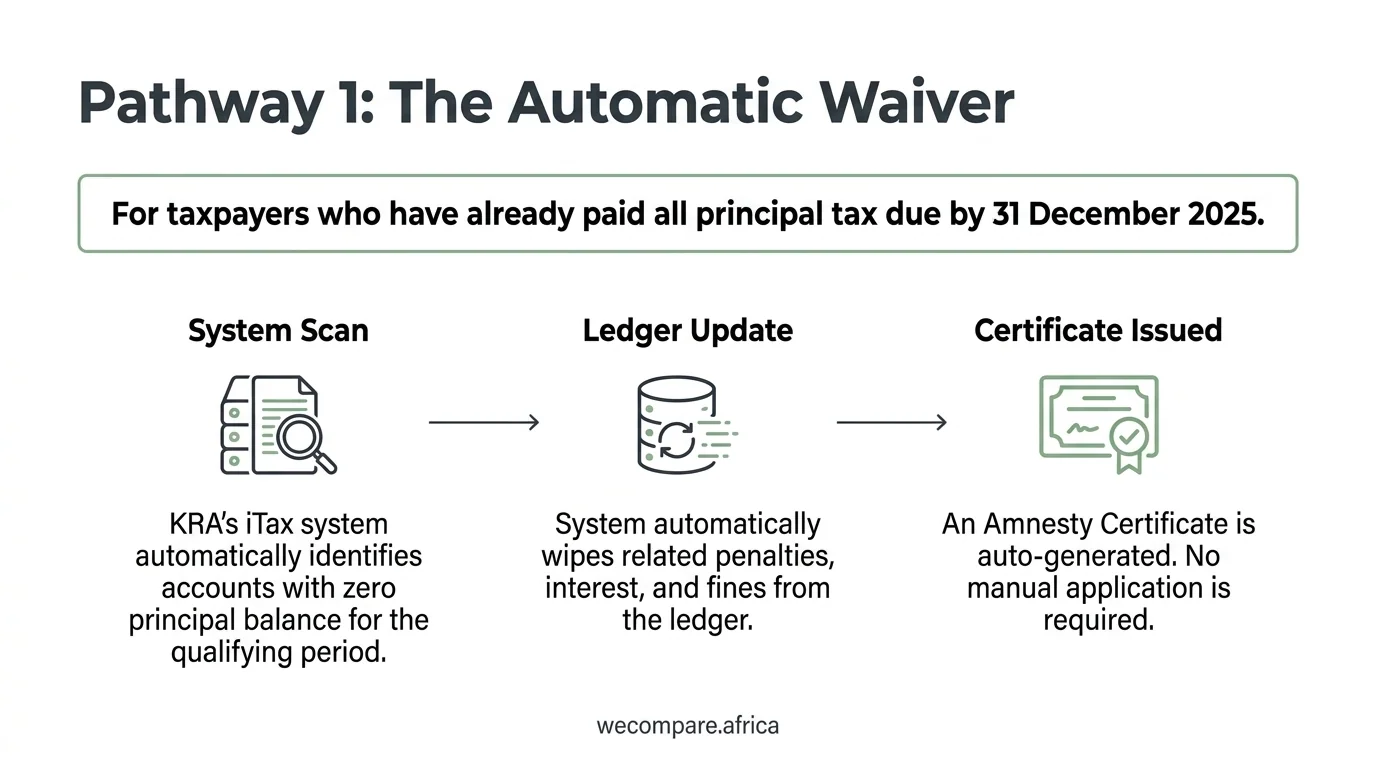
To download the certificate, go to Taxpayer Profile, then Useful Links, then Consult and Reprint Acknowledgement Receipts and Certificates, then Debt and Enforcement, then Amnesty Certificate.
Pathway 2: resolving unpaid principal
If you still owe principal, you have two routes. You can pay the full balance in one transaction during the window, and the waiver follows once it clears. Or you can apply for a payment plan on iTax and clear the principal in instalments, finishing by 31 December 2026.
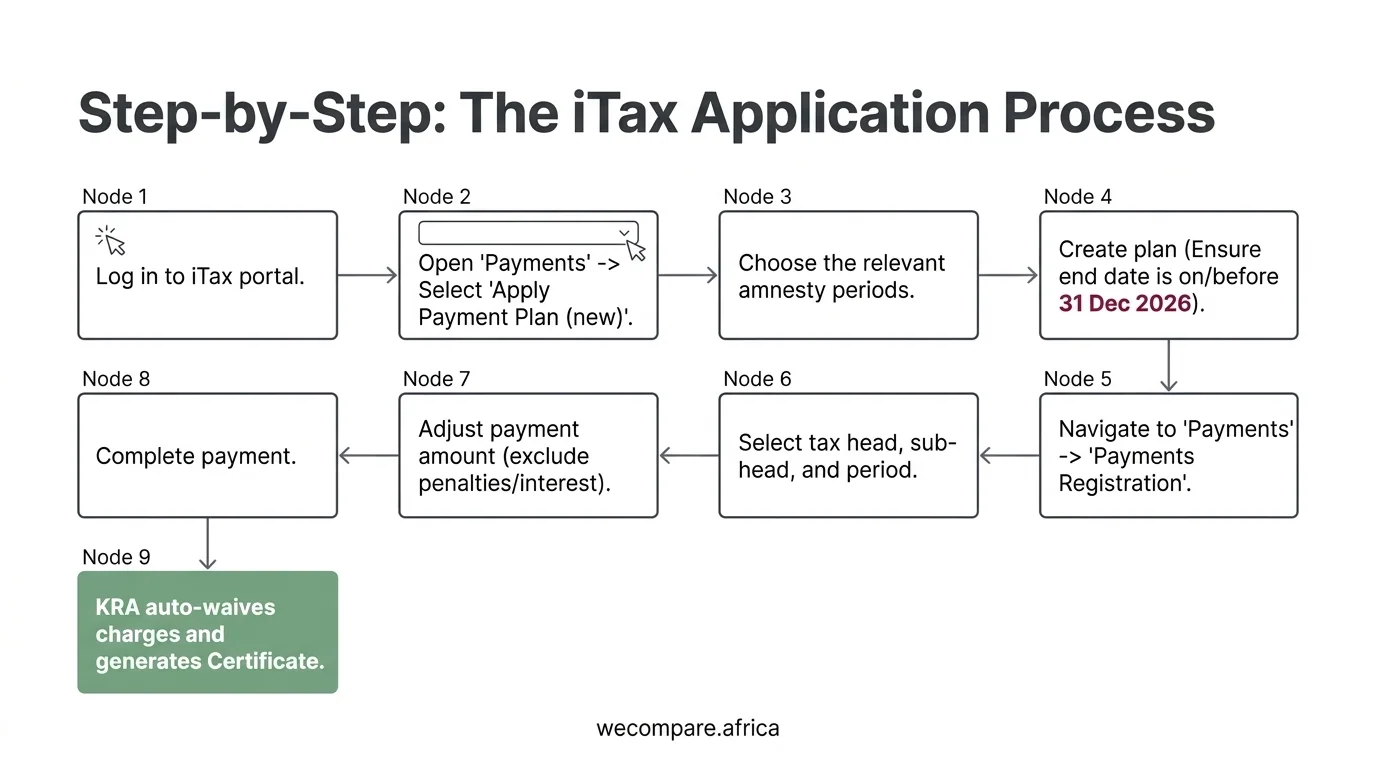
How to apply on iTax, step by step
For a payment plan, follow the steps below. When you register the payment, change the amount so it covers the principal only. KRA warns that penalties, interest or fines paid by mistake cannot be refunded or moved to another tax.
Structuring a payment plan: apply early
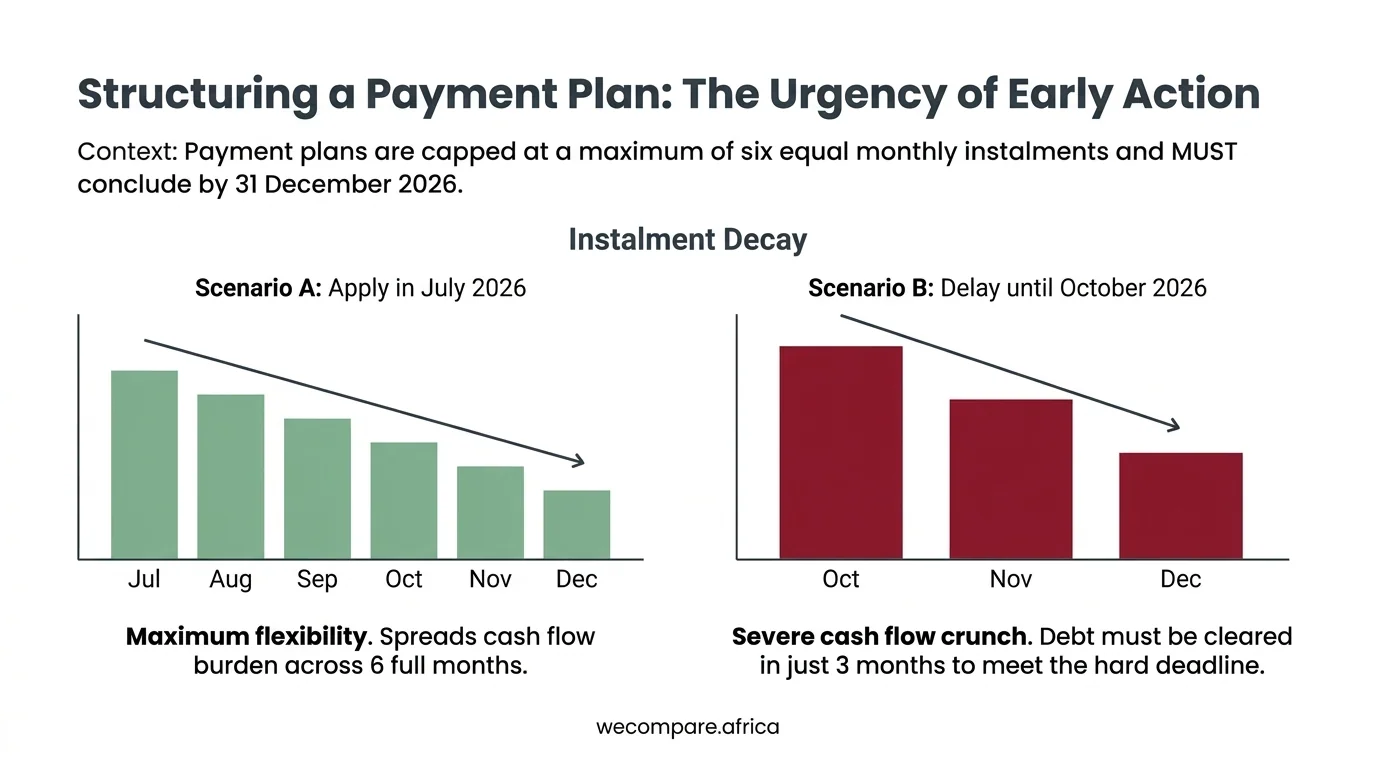
KRA says a plan applied for in July 2026 can have a maximum of 6 instalments. Because every plan must end by 31 December 2026, each month you wait removes an instalment. Applying later means larger payments over a shorter period.
Unfiled returns and disputes
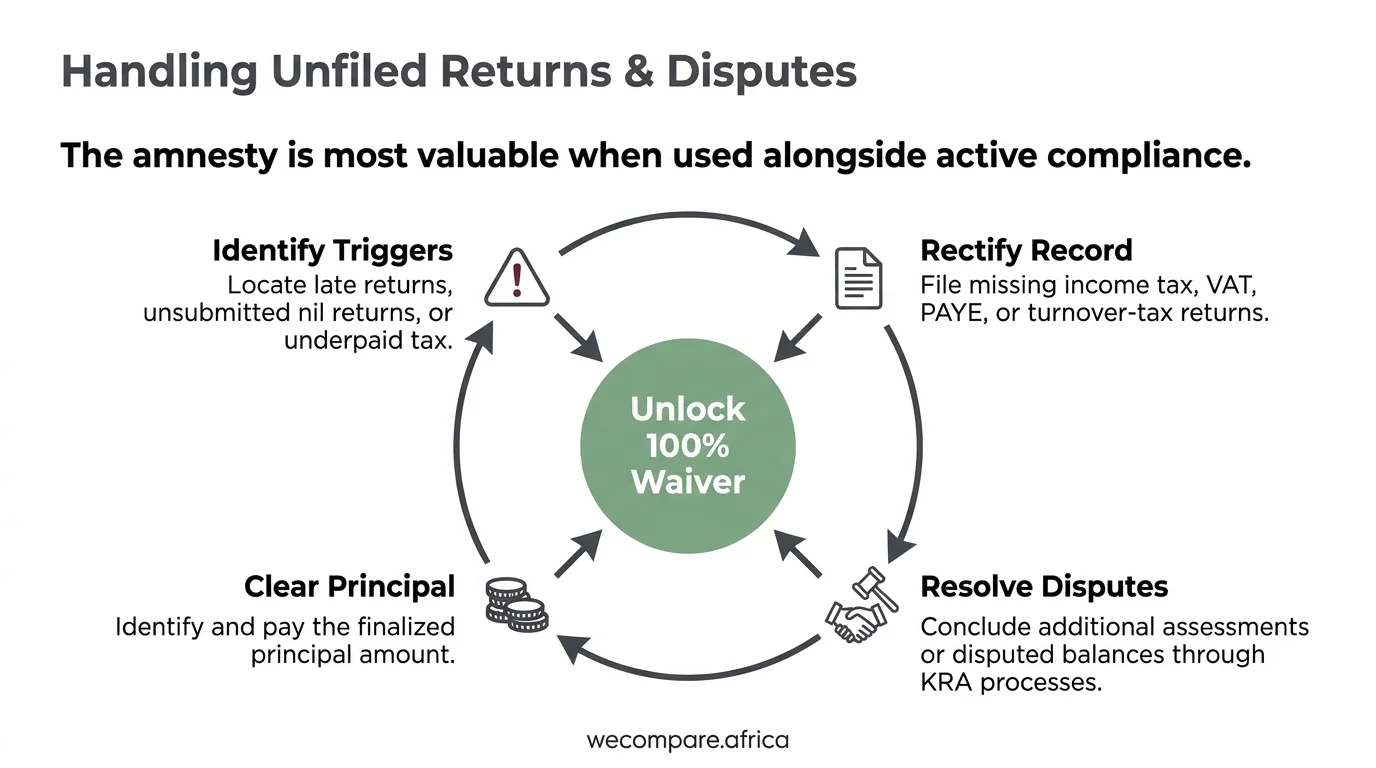
The amnesty works best alongside active compliance. File any missing income tax, VAT, PAYE or turnover tax returns for periods up to 31 December 2025. Nil returns qualify automatically. If filing creates a tax liability, the return qualifies once that principal is paid by 31 December 2026. If you have an objection, appeal or alternative dispute resolution case, it qualifies once it is concluded and the agreed principal is paid by the same date.
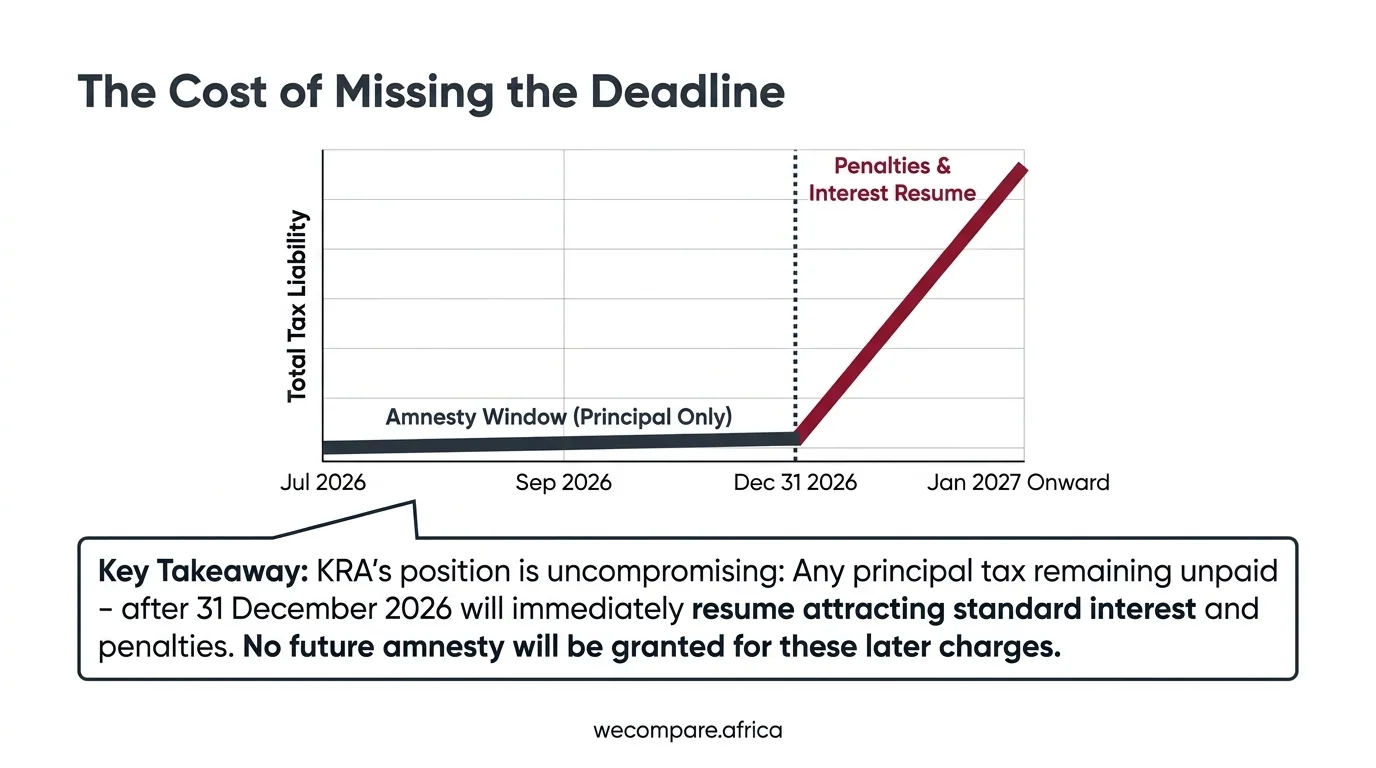
The cost of missing the deadline
KRA's position is firm. Principal still unpaid after 31 December 2026 will resume attracting standard interest and penalties, and no amnesty will be granted on those later charges.
2024 amnesty vs 2026 amnesty
This is Kenya's third amnesty window. The Finance Act 2023 amnesty covered periods up to 31 December 2022 with a principal deadline of 30 June 2024. The Tax Procedures (Amendment) Act 2024, effective 27 December 2024, extended it to periods up to 31 December 2023, with principal due by 30 June 2025. The 2026 amnesty moves both dates forward again.
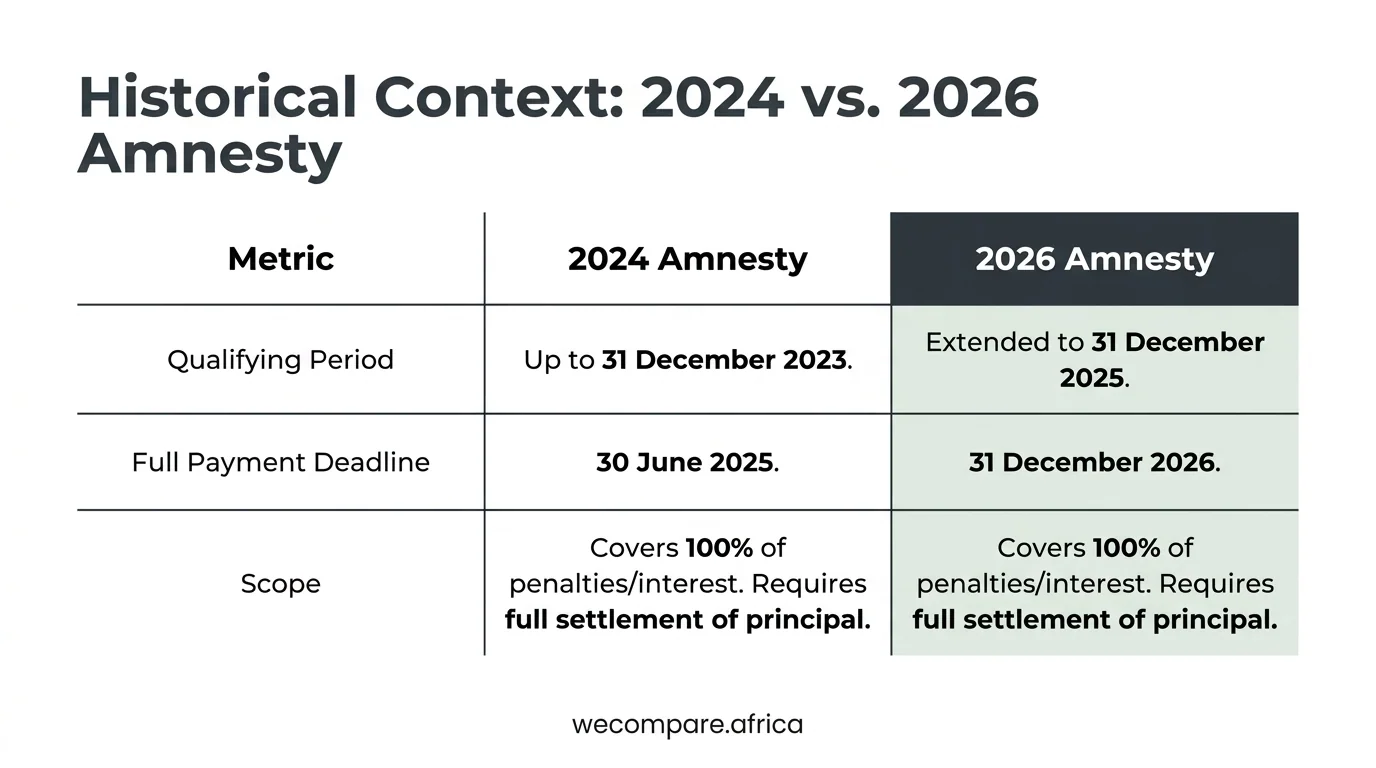
| Metric | 2024 amnesty | 2026 amnesty |
|---|---|---|
| Law | Tax Procedures (Amendment) Act 2024 | Finance Act 2026 |
| Qualifying period | Up to 31 December 2023 | Up to 31 December 2025 |
| Principal payment deadline | 30 June 2025 | 31 December 2026 |
| Condition | Full settlement of principal | Full settlement of principal |
Frequently asked questions
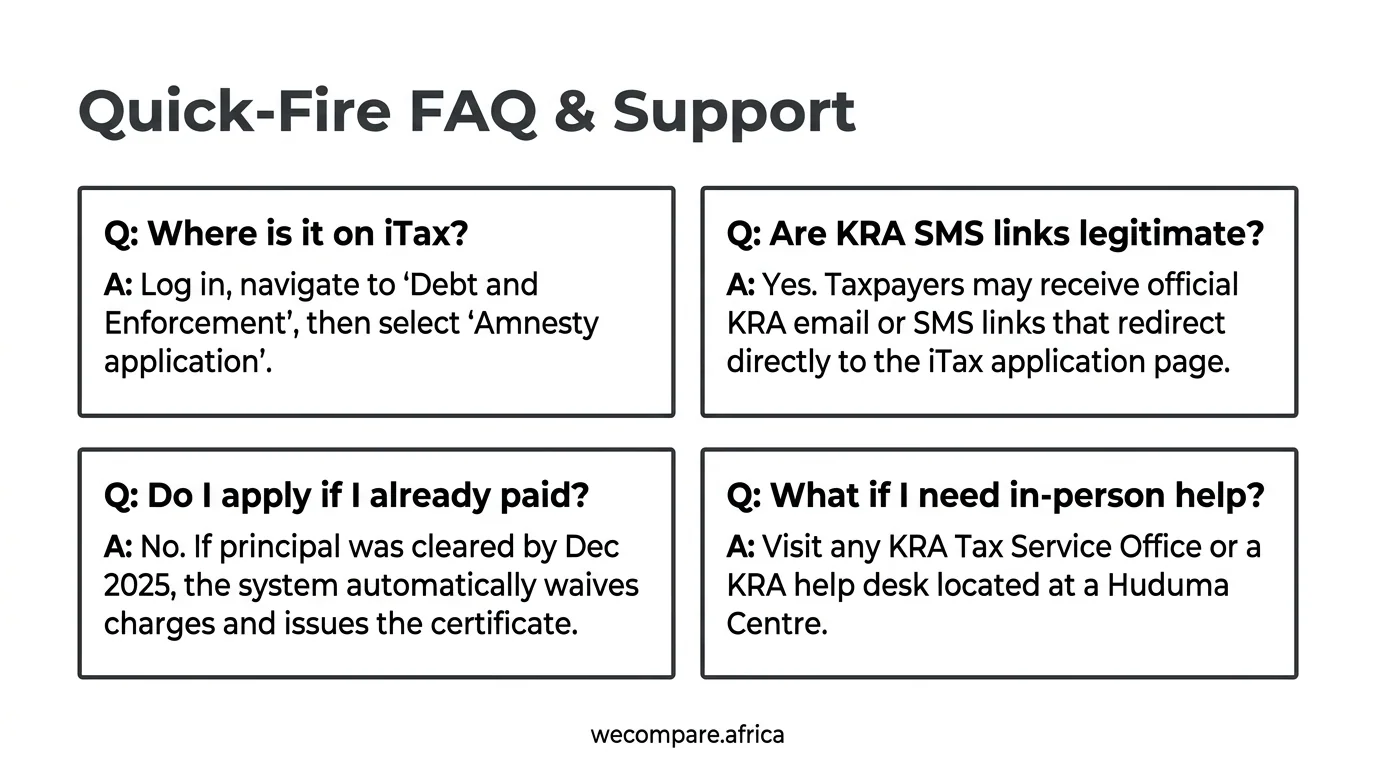
Do I need to apply if I already paid my principal tax?
No. If you cleared all principal for periods up to 31 December 2025, iTax waives the related penalties, interest and fines automatically and issues the certificate.
Where is the amnesty application on iTax?
Log in, go to Debt and Enforcement, then select Amnesty application. For instalments, use Payment, then Apply Payment Plan (new).
Is the principal tax waived?
No. Only penalties, interest and fines are waived. The principal must be paid in full by 31 December 2026.
Can I pay in instalments?
Yes, through an iTax payment plan. A plan applied for in July 2026 can have up to 6 instalments, and every plan must be fully paid by 31 December 2026, so a later application gets fewer instalments.
Why do I still see penalties on my ledger?
KRA has said the waiver is still being rolled out for some penalties, especially late-filing penalties, and that seeing them does not mean you were denied the amnesty. If you only have late-filing penalties, file all pending returns and they are waived automatically.
What happens if I miss 31 December 2026?
Unpaid principal attracts interest and penalties again, and no amnesty is granted on those later charges.
Does it cover customs duties?
No. Customs duties under the East African Community Customs Management Act and agency revenues are excluded.
Are KRA SMS and email links genuine?
KRA says it may send email or SMS links that lead to the iTax application page. If you are unsure, type the iTax address into your browser yourself instead of clicking.
Where can I get in-person help?
Visit any KRA Tax Service Office or the KRA help desk at a Huduma Centre. You can also call 020 4 999 999 or 0711 099 999, or email callcentre@kra.go.ke.
Your 2026 compliance checklist
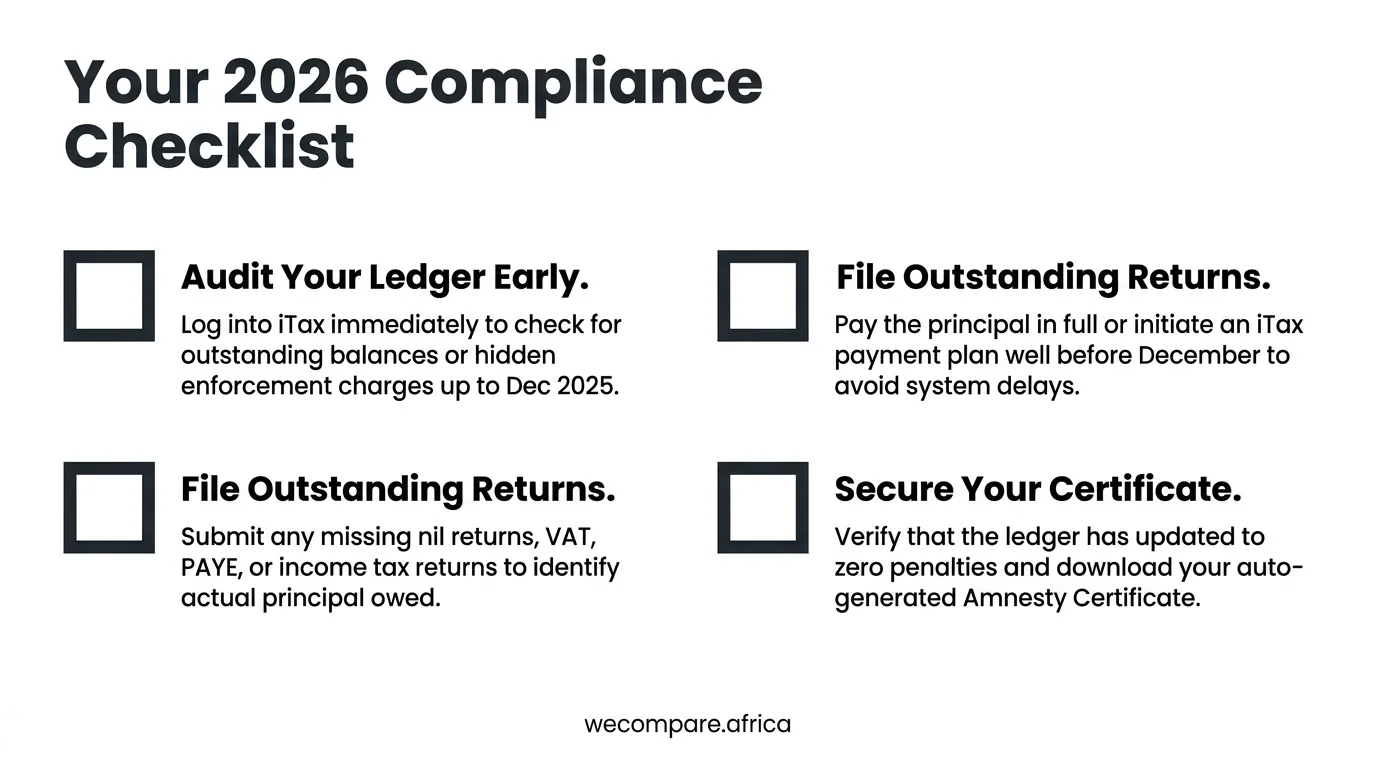
- Audit your ledger early. Log in to iTax and check for principal, penalties and interest up to 31 December 2025.
- File outstanding returns. Submit missing nil, VAT, PAYE or income tax returns so you know the real principal owed.
- Pay the principal or start a payment plan. Do it well before December to avoid system delays.
- Secure your certificate. Confirm penalties show as zero on your ledger and download the amnesty certificate.
This article is general information based on KRA's published guidance, not tax advice. Rules and iTax steps can change, so confirm your own position on iTax or with KRA before you pay.
Sources
- KRA: 2026 Tax Amnesty Programme at a Glance
- KRA: Taxpayer guidelines on the implementation of Tax Amnesty 2026
- Kenyans.co.ke: KRA announces six-month tax amnesty (3 July 2026)
- Kenyans.co.ke: Why taxpayers still see penalties on iTax (29 July 2026)
- EY Tax News: Kenya extends tax amnesty until 30 June 2025
Figures last verified 9 November 2026.
Join the discussion
Please do not share account numbers, phone numbers, links or other personal details. Comments are general discussion, not advice. All comments are reviewed before they appear, and we may remove comments that break these rules.