Saving & SACCOs
The Best SACCOs in Kenya 2026: How to Choose, Verify and Compare
The highest dividend is not the best SACCO. Here is how to check a SACCO's SASRA licence, compare reported 2025 returns on shares and deposits, understand loan multipliers, and spot the red flags before you join.
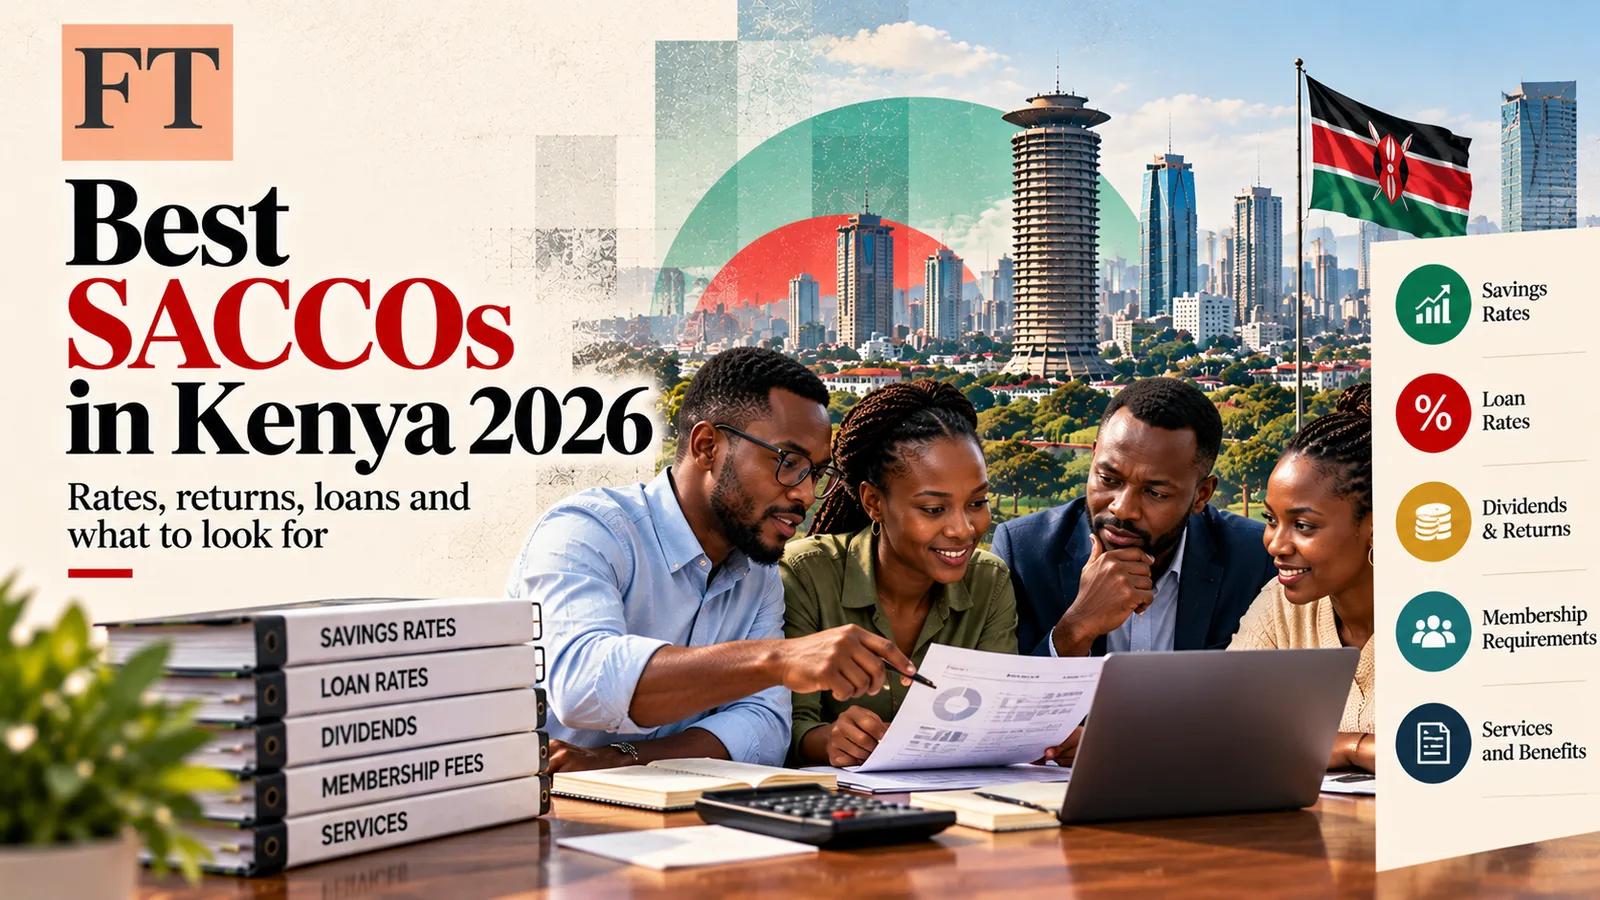
What makes a great SACCO: five pillars
Dividend is one input among five. A SACCO that pays well but is poorly regulated, thinly capitalised or hard to reach will cost you more than it earns.
If you would rather keep your savings in a bank than join a SACCO, compare the best savings accounts in Kenya first, then weigh them against the SACCO options below.
Read this slide as text
- Regulatory standing: must hold a valid SASRA licence for the specific activity offered.
- Financial strength: backed by audited accounts, capital adequacy, liquidity and solid loan-book quality.
- Returns: combines dividend on share capital and interest on deposits.
- Credit value: loan multiplier, interest rate, fees, guarantors and approval speed.
- Access and service: eligibility breadth, digital banking, paybill channels and customer support.
Verify the SASRA licence first
SASRA, the Sacco Societies Regulatory Authority, is the statutory regulator. Its 2026 notice, reported on 3 February 2026, lists 176 SACCOs licensed for deposit-taking business and another 176 authorised for non-deposit-taking business. It also restricted five SACCOs for 12 months, limiting them to credit-only operations with no new member deposits, and recorded two more as revoked or ceased.
Check SASRA's official list, not a screenshot or a WhatsApp forward.
Read this slide as text
- Go to the official SASRA website.
- Open the 2026 licensed and authorised SACCO list.
- Search the exact legal name matching the certificate, app and paybill.
- Confirm deposit-taking status (FOSA or withdrawable deposits require a licence).
- Check the licence certificate for validity dates and reference numbers.
- Cross-check SASRA records with the SACCO’s latest annual report and AGM notices.
What the licence labels mean
Read this slide as text
- Licensed DT-SACCO: licensed to take deposits and operate FOSA services. Confirm it appears on the official licensed list.
- Authorised NWDT-SACCO: authorised for specified non-deposit-taking or non-withdrawable deposit business. Confirm the activity suits your savings goal.
- Restricted SACCO: permitted to operate subject to conditions. Read the restriction and ask in writing how it affects your money and access.
- No longer authorised: not permitted to continue regulated SACCO business. Avoid new deposits and seek official clarification first.
Shares versus deposits: how returns work
A SACCO pays a dividend on your share capital and interest on your deposits. They are separate pots with separate rules.
Read this slide as text
- Share capital: generates dividends; generally not withdrawable; requires selling or transferring to exit.
- Savings/deposits: generate interest; can be withdrawn, subject to SACCO terms and loan attachments.
Your real return depends on how your money is split between these two buckets. A high dividend on shares means little if your funds are entirely locked and you cannot access them.
Reported 2025 returns, and a calculator
The table lists the payouts we could confirm in published reports for the 2025 financial year, announced from January 2026. Rates are set at each SACCO's annual general meeting and change every year.
| SACCO | Dividend on shares | Interest on deposits |
|---|---|---|
| Tower SACCO | 20% | 13% |
| Kenya Police DT SACCO | 17% | 11% |
| Hazina SACCO | 17% | 10.75% |
| Stima SACCO | 16% | 11% |
| Harambee SACCO | 15% | 9.1% |
| Mwalimu SACCO | 13% | 10.05% |
Source: Money254 (26 January 2026), with Stima, Harambee and Mwalimu cross-checked against Serrari Group and Police DT against Capital FM. Harambee's deposit rate is shown as 9.1% by Money254 and as 9.1% to 10% by Serrari. SACCO names are as published by those sources.
Blended return calculator
Dividend earned
–Interest earned
–Total return
–Blended rate
–Worked example with Stima's reported rates: KES 100,000 in shares at 16% earns KES 16,000. KES 100,000 in deposits at 11% earns KES 11,000. Total KES 27,000 on KES 200,000, a blended 13.5%. These are headline rates before any tax. Payouts depend on audited surplus and are not guaranteed.
The loan multiplier
Most SACCOs let you borrow a multiple of your eligible savings. The multiplier tells you how much, not how much it costs.
Read this slide as text
- Input: KES 100,000 eligible balance.
- 2x multiplier: KES 200,000 (conservative borrowing capacity).
- 3x multiplier: KES 300,000 (common standard among many Kenyan SACCOs).
- 4x multiplier: KES 400,000 (generous; often tied to employer check-off or strong credit).
Before applying, compare: 1. annual reducing-balance interest rate; 2. processing fees and insurance charges; 3. loan processing time; 4. guarantor requirements; 5. penalties for late repayment; 6. whether the multiplier is based on deposits, shares or both.
Ask which balance the multiplier applies to. A SACCO that multiplies deposits only is far less generous than one that counts shares and deposits together.
How to join a SACCO safely
- Confirm eligibility. Check whether the SACCO is open to all Kenyans or restricted by profession or employer.
- Run the SASRA check. Search the exact legal name on SASRA's 2026 list.
- Get official forms. Download them from the SACCO's official website or branch, not from unofficial agents.
- Prepare documents. ID, KRA PIN, a photo and payslips or M-Pesa statements.
- Pay the entry costs. The deck behind this guide cites registration fees of KES 500 to 2,000 and minimum share capital of KES 1,000 to 10,000. Treat that as a typical range and confirm the figures with the SACCO.
- Contribute consistently. Use payroll check-off, standing orders or M-Pesa.
- Expect a waiting period for loans. Many SACCOs want about 3 to 6 months of active contributions first. Ask for the exact rule.
- Know your exit. Read the rules on withdrawing, transferring or selling share capital before you pay anything.
Red flags: when to walk away
Read this slide as text
Critical red flags
- No valid 2026 SASRA licence for the activity offered.
- "No longer authorised" status on the SASRA list.
- Unexplained restricted status (get clarification in writing).
- Missing or delayed audited accounts. Dividends must be supported by audited surplus.
- Unrealistic guaranteed returns that far exceed established peers.
Operational warning signs
- Weak liquidity or poor loan-book quality (high non-performing loans).
- Unclear share-capital exit rules.
- Mismatched payment channels: paybills and accounts must match the registered legal name.
- Pressure to recruit or "invest urgently". A SACCO is a cooperative, not a scheme.
- Poor complaint handling (delayed loans, blocked withdrawals).
Which SACCO might suit you
The best SACCO depends on who you are. The slide below matches common member groups to SACCOs that serve them. It is a starting shortlist, not a ranking or a recommendation.
Read this slide as text
- Best all-round open option: Stima SACCO (combines access, reported returns and loan capacity).
- Best headline dividend (open): Tower SACCO (requires verifying the latest liquidity position).
- Best for teachers: Mwalimu National SACCO.
- Best for police officers: Kenya Police DT SACCO.
- Best for civil servants: Harambee SACCO.
- Best low-entry open option: Unaitas SACCO or Wananchi SACCO (compare loan pricing carefully).
- Best for corporate professionals: Safaricom, Kenya Bankers, Hazina or Afya SACCO (subject to employer eligibility).
Final due-diligence checklist
Read this slide as text
- The SACCO’s exact legal name appears on SASRA’s official 2026 list.
- Licence status is valid for 2026 and matches the exact service offered.
- Any SASRA restrictions have been explained in writing.
- Latest audited accounts and AGM dividend declarations are available and reviewed.
- I clearly understand the split and rules between share capital and deposits.
- I know the loan multiplier, total loan cost and repayment terms.
- I have a clear, documented plan for exiting or transferring my share capital.
A disciplined approach: SASRA verification first, audited financials second, product terms third.
Why we do not publish a score ranking
You will see "top 10" and "top 20" SACCO lists with scores out of 10. We chose not to publish one. A fair score needs each SACCO's audited capital, liquidity and non-performing loans for the same year, plus its loan pricing and service data. We do not have that for every SACCO on a typical list, and ratings built without it only look precise. Instead, this guide gives you the verified payouts above, the checks that matter, and the SASRA list so you can compare for yourself.
Frequently asked questions
How do I check whether a SACCO is licensed in Kenya?
Search the SACCO's exact legal name on SASRA's official list of licensed and authorised SACCOs for 2026, then confirm that its licence covers the service it offers.
Which SACCO pays the highest dividend in Kenya?
Among the payouts we could confirm for the 2025 financial year, Tower SACCO reported 20% on shares and 13% on deposits. A high rate does not guarantee a safe SACCO, so check the licence, liquidity and audited accounts too.
What is the difference between a dividend and interest on deposits?
A dividend is paid on your share capital, which is generally locked. Interest is paid on your savings or deposits, which can usually be withdrawn subject to the SACCO's terms and any loans they secure.
Can I withdraw my share capital?
Generally not. Share capital is usually returned only when you exit, often by transferring or selling your shares. Read the SACCO's by-laws on this before you join.
What is a loan multiplier?
It is the number of times your eligible savings you can borrow. With KES 100,000 eligible and a 3x multiplier, you could borrow up to KES 300,000. Always compare the interest rate, fees and guarantor rules as well.
Are SACCO dividends guaranteed?
No. Dividends are declared at the annual general meeting from audited surplus and change from year to year.
How we researched this guide
This is an independent, source-based guide. We checked the 2026 SASRA licensing figures and the 2025 SACCO payouts against published news reports in October 2026, and we only list a rate when a published source confirms it. We did not score or rank SACCOs. Rules, rates and eligibility change, so confirm everything with SASRA and the SACCO itself. Contact the editor to report an error or an out-of-date figure.
Sources
- SASRA, Sacco Societies Regulatory Authority (official licensed and authorised lists)
- Kenyans.co.ke, SASRA publishes list of authorised SACCOs, restricts and revokes licences of 7 others (3 February 2026)
- Money254, SACCOs with the highest dividends in 2026 as announced so far (26 January 2026)
- Serrari Group, SACCO dividend rates Kenya 2026
- Capital FM, Police DT SACCO assets hit Sh66.6bn, pays Sh4.1bn to members (February 2026)
Join the discussion
Please do not share account numbers, phone numbers, links or other personal details. Comments are general discussion, not advice. All comments are reviewed before they appear, and we may remove comments that break these rules.