Banking & payments
How I&M Bank Kenya Grew Deposits 18% With Free M-PESA Transfers
I&M's deposits rose 18% to KSh 505bn in H1 2026, helped by digital onboarding and free M-PESA transfers. How it works and how rivals compare.
I&M Bank Kenya is part of I&M Group, whose deposits grew 17.4% in FY2025 to KSh 484bn and 18% in H1 2026 to KSh 505bn, helped by digital onboarding and free transfers to M-PESA and Airtel Money. The growth is real: group profit after tax rose 24.5% to KSh 19.8bn in FY2025 and 22% to KSh 10.2bn in H1 2026.
How I&M is winning deposits
| Step | What I&M did | Result |
|---|---|---|
| Acquire | Frictionless digital onboarding | 92% of customers digitally active (H1 2026) |
| Engage | Free transfers to M-PESA and Airtel Money | Free transfers give customers a reason to keep transacting with the bank |
| Grow | Payments turned into a low-cost deposit funnel | Group deposits +18% to KSh 505bn (H1 2026) |
I&M's MSME revenue rose 41%. Its wealth management assets under management rose 81% to KSh 127bn and wealth revenue rose 145% to KSh 481m in H1 2026 (Business Watch).
The FY2025 full-year picture
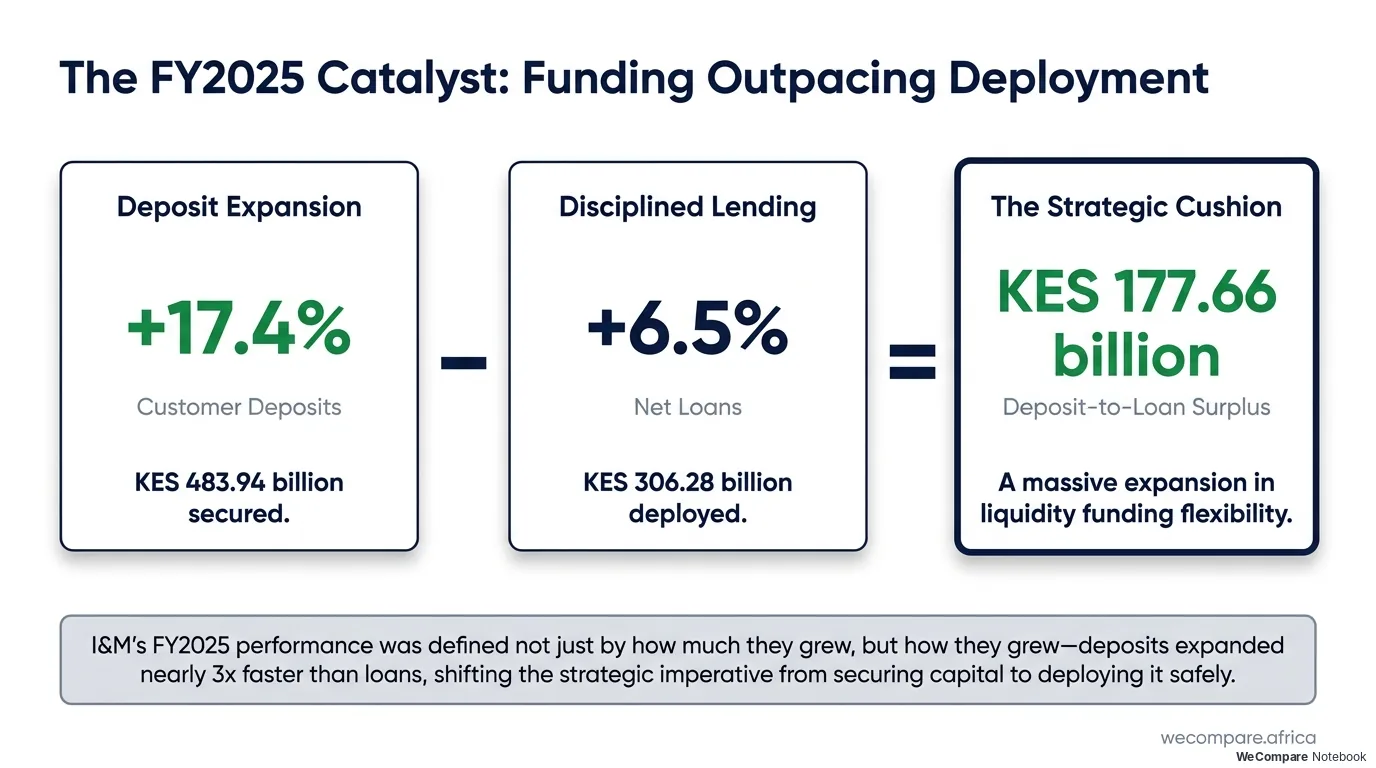
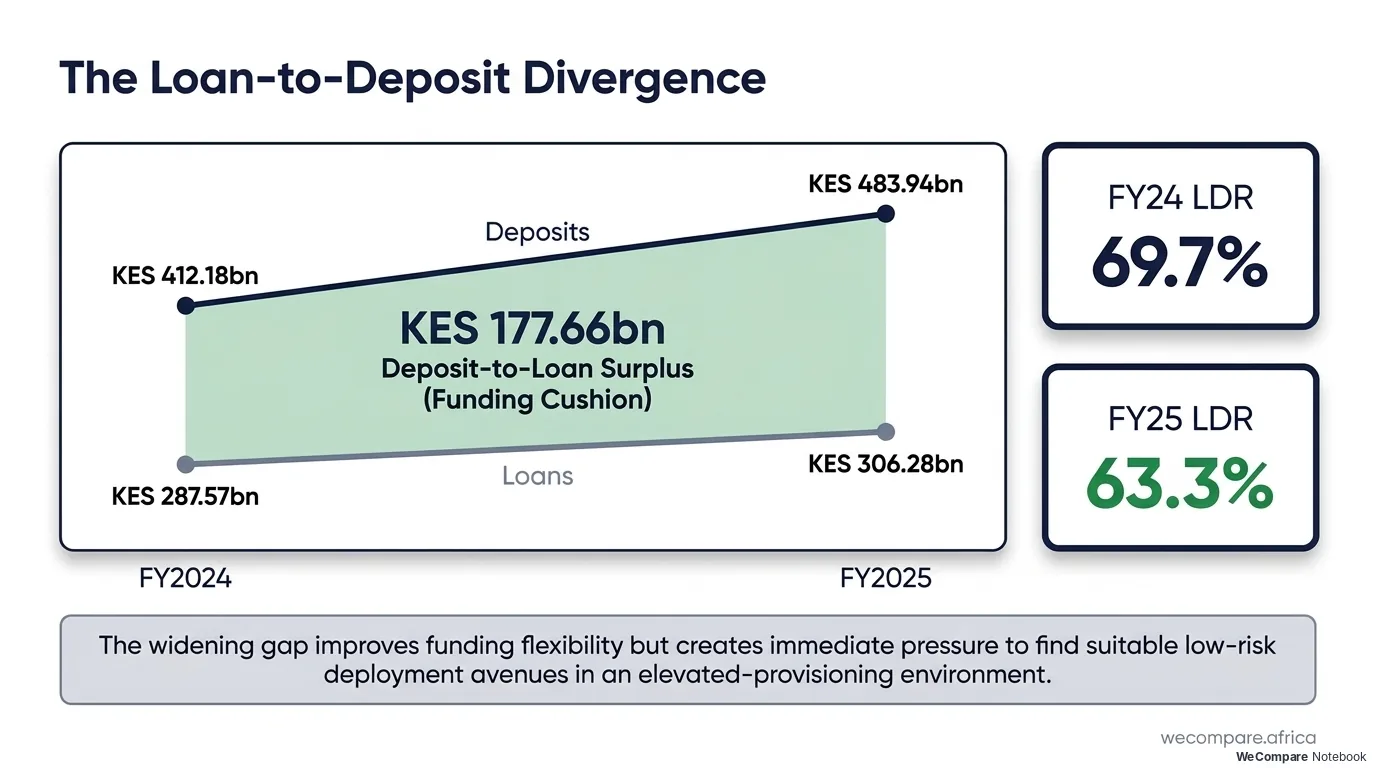
The 2025 results show the deposit push working before the half-year numbers. Customer deposits rose 17.4% to KSh 483.9bn while net loans grew only 6.5% to KSh 306.3bn, so deposits grew nearly three times as fast as lending. The loan-to-deposit ratio fell from 69.7% to 63.3%, leaving a funding cushion of about KSh 177.7bn that I&M now has to lend out or invest.
| FY2025 | FY2024 | FY2025 | Change |
|---|---|---|---|
| Profit before tax | KSh 19.8bn | KSh 24.2bn | +22.4% |
| Profit after tax | KSh 15.9bn | KSh 19.8bn | +24.5% |
| Total operating income | KSh 50.6bn | KSh 60.3bn | +19.2% |
| Non-interest income | KSh 11.0bn | KSh 14.4bn | +30.8% |
| Customer deposits | KSh 412.2bn | KSh 483.9bn | +17.4% |
| Net loans | KSh 287.5bn | KSh 306.3bn | +6.5% |
| Gross NPL ratio | 11.5% | 9.6% | Improved |
| Cost-to-income (excluding provisions) | 47.3% | 46.8% | Improved |
Cost of funding fell from 6.7% to 4.7% and net interest margin rose to 8.5% from 8.1%, which is why profit grew faster than lending. Part of the surplus went into government securities, up 55.5% to KSh 159.4bn. The board raised the total dividend to KSh 3.75 a share from KSh 3.00.
Is it paying off?
At group level, yes. Profit after tax rose 24.5% to KSh 19.8bn in FY2025 and 22% to KSh 10.2bn in H1 2026, and net NPLs improved to 2.3% at H1 2026, the lowest net risk profile among the banks compared.
Kenya carries the cost of the push. I&M Bank Kenya produces 67% of group profit before tax, and local loan provisions jumped 34% to KSh 4.2bn in H1 2026 while operating expenses rose 21%. Group loan-loss provisions also rose 11.1% to KSh 8.7bn in FY2025, and once provisions are included the cost-to-income ratio is 61.2%.
The group growth came mostly from regional units. Rwanda profit before tax rose 53% to KSh 2.4bn and Uganda rose 225% from a small base in H1 2026. Together, regional units now supply 33% of group profit before tax, up from 25%.
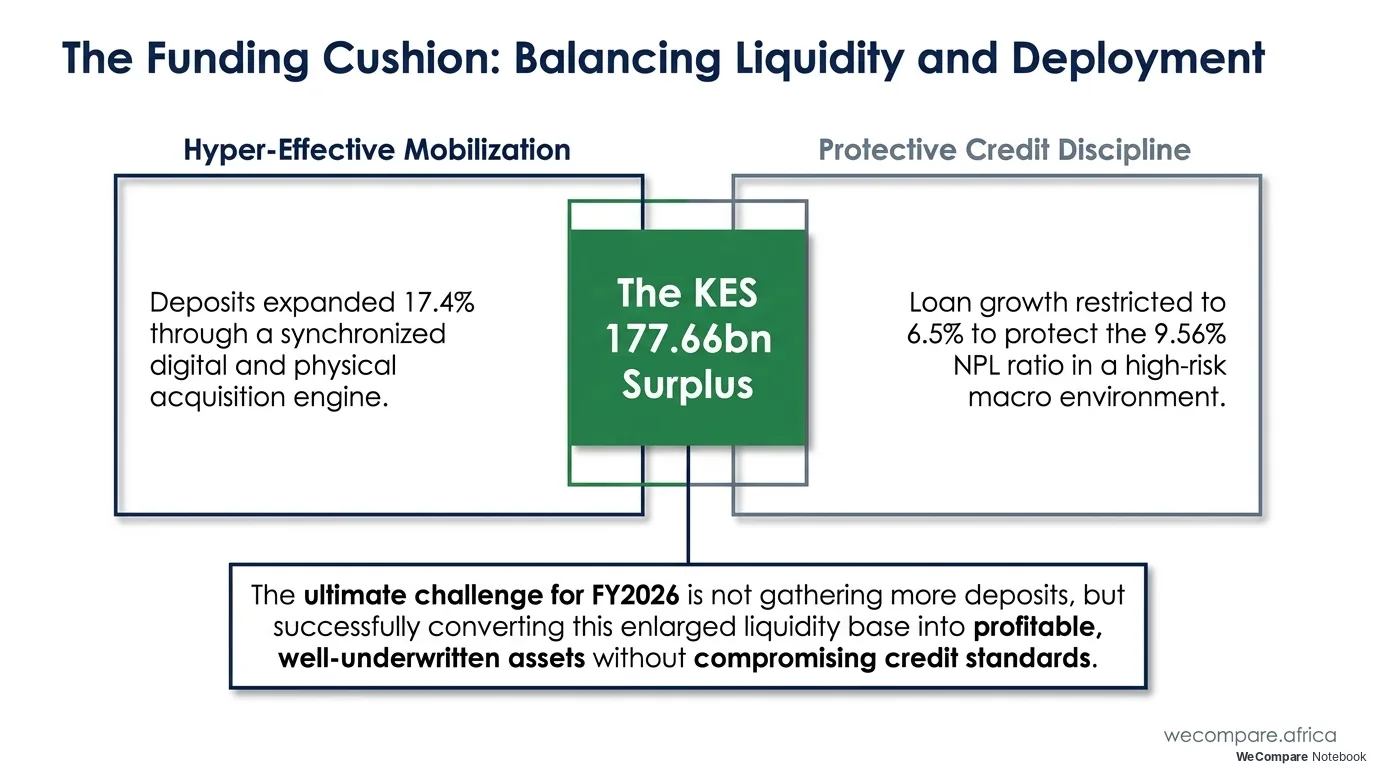
The open question for 2026 is what I&M does with the surplus. Deposits are cheap, but they only pay off if they become well-underwritten loans.
How rivals compare on deposits
| Bank | H1 2026 deposits | Growth | How they did it |
|---|---|---|---|
| Stanbic Kenya | KSh 422bn | +28% | Core banking upgrade and corporate cash-management integration |
| Equity Group | KSh 1.59tn | +21% | Biometric retail authentication and an 89.7% digital user base |
| I&M Group | KSh 505bn | +18% | Digital onboarding and free mobile-money transfers |
| KCB Group | KSh 1.71tn | +15.1% | Retail acquisition, mobile credit and its Pesapal alliance |
| Absa Kenya | KSh 381bn | +5% | Not covered in this comparison |
NCBA took a different route: it moved from costly fixed-term deposits to transactional accounts with cheaper PesaLink pricing. I&M's 18% growth beats KCB and StanChart but trails Stanbic and Equity, so it is defending its share rather than pulling away.
For FY2025, the contrast with StanChart is sharp: I&M's deposits grew 17.4% while StanChart's fell 4.1%, and I&M's profit before tax rose 22.4% while StanChart's fell 40.3%. StanChart's gross NPL ratio is lower (5.5% against 9.6%), so it traded growth for quality. Read Is Standard Chartered Kenya leaving?.
What it means for customers
Free transfers to M-PESA and Airtel Money are the clearest customer benefit of this competition. Banks want your transactions because they bring cheap deposits. Before you switch for free transfers, check the fees on other services, the minimum balance and the savings interest rate.
Keep reading
- Kenya bank performance H1 2026: the Tier-1 hub analysis
- Best savings accounts in Kenya
- Equity vs KCB: how Kenya's two biggest banks make money
- Is Standard Chartered Kenya leaving?
- CBK rate at 8.75%: what falling interest rates mean for savers and borrowers
Frequently asked questions
How did I&M grow deposits 18% in H1 2026?
Through frictionless digital onboarding, with 92% of customers digitally active, plus free transfers to M-PESA and Airtel Money. Group deposits rose 18% to KSh 505bn. Deposits had already grown 17.4% to KSh 484bn in FY2025.
Is I&M's profit growing?
Yes, at group level: profit after tax rose 24.5% to KSh 19.8bn in FY2025 and 22% to KSh 10.2bn in H1 2026. I&M Bank Kenya produces 67% of group profit before tax, and its local loan provisions jumped 34% to KSh 4.2bn in H1 2026 while operating expenses rose 21%.
Where is I&M's profit growth coming from?
Mostly regional units. Rwanda profit before tax rose 53% to KSh 2.4bn and Uganda rose 225% from a small base in H1 2026. Regional units now supply 33% of group profit before tax, up from 25%.
How does I&M's deposit growth compare with its rivals?
In H1 2026 Stanbic Kenya grew deposits 28%, Equity Group 21%, I&M Group 18%, KCB Group 15.1% and Absa Kenya 5%. I&M beats KCB and StanChart but trails Stanbic and Equity.
What is I&M's loan-to-deposit ratio?
63.3% at end-2025, down from 69.7%, because deposits grew 17.4% while net loans grew 6.5%. That leaves about KSh 177.7bn of funding to deploy.
Should I switch banks for free M-PESA transfers?
Free transfers to M-PESA and Airtel Money are the clearest customer benefit of this competition, but check the fees on other services, the minimum balance and the savings interest rate before you switch.
Sources
- CBK MPC press release, 7 October 2026
- I&M Group H1 2026: profit up 15% as deposits cross KSh 500bn (The Business Watch)
- Stanbic Holdings H1 2026 results (Bizna Kenya)
- Stanbic Kenya H1 2026: net profit rises to KSh 6.6bn (Capital FM)
- Equity Group Holdings HY 2026 investor booklet
- KCB Group H1 2026 results: profit before tax rises 20.8% (Biashara Leo)
- KCB Group H1 2026: net profit up 14% to KSh 36.9bn (Business Today)
- Standard Chartered Bank Kenya H1 2026 results (Khusoko)
- I&M Group FY2025 earnings note (Cytonn)
- I&M Group FY2025: net profit up 24% to KSh 19.8 billion (Khusoko)
- Standard Chartered Bank Kenya FY2025 earnings note (Cytonn)
- I&M Bank removes charges for mobile money transfers to/from M-Pesa and Airtel Money (HapaKenya)
Disclaimer: This article is published for educational, informational and news purposes only. The metrics, ratios and commentary do not constitute investment, tax, legal or financial advice. Consult a licensed financial adviser before making decisions about listed securities.
Join the discussion
Please do not share account numbers, phone numbers, links or other personal details. Comments are general discussion, not advice. All comments are reviewed before they appear, and we may remove comments that break these rules.